Reasons Behind the Recent Increase in Your Card’s Interest Rate
Wondering why your credit card interest rate increased? Discover the usual reasons behind the hike, important regulations to be aware of, and practical tips to reduce the cost on your balance.
What to Know About Rising Credit Card Interest Rates
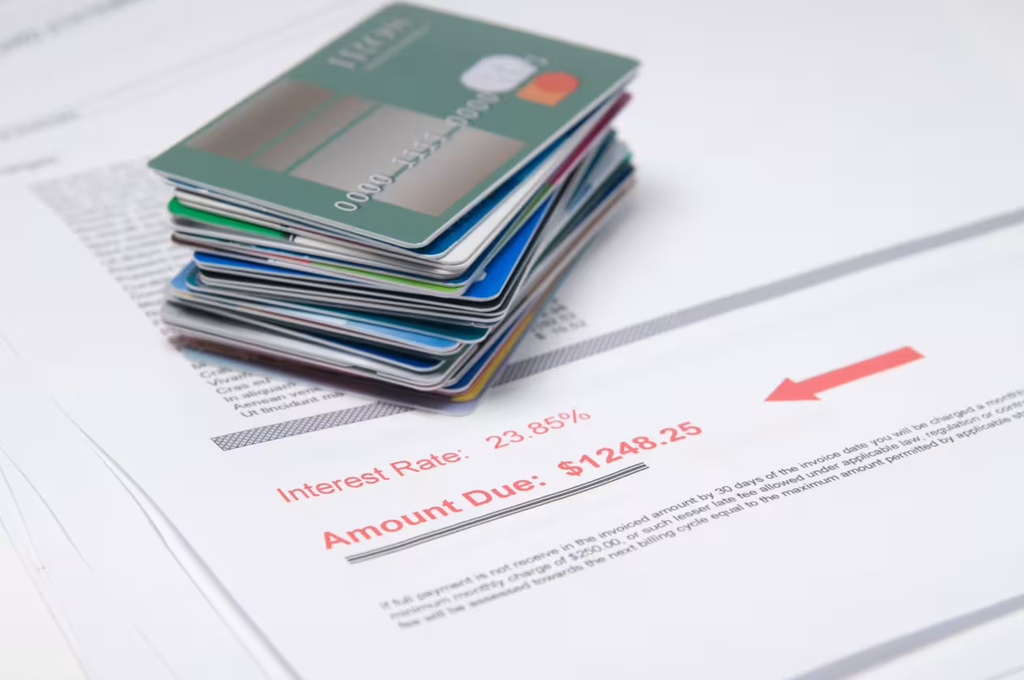
If your credit card’s interest rate suddenly seems higher, it’s not just your imagination—and it doesn’t always mean your credit score has dropped.
There are several reasons why credit card APRs can change. Your card might have a variable APR linked to an index, a promotional rate could have ended, or a late payment might have caused your rate to increase in specific situations.
When the interest rate on a revolving balance rises, even a modest increase can make carrying debt more costly.
If you opened your statement wondering, “Why did my APR just increase?”, here’s a look at possible reasons—and what steps you can take next.
What Causes Your Credit Card Interest Rate to Increase?
There isn’t one universal reason why every cardholder’s APR rises. The key is to identify the kind of rate you have and what triggered the change in your account.
Here are the most frequent reasons:
- Your card has a variable APR and its underlying index increased;
- A promotional or introductory APR ended;
- You were more than 60 days late on a payment;
- Your card issuer changed the rate on new purchases after providing required notice;
- A special rate associated with a payment arrangement changed or ended.
The CFPB states that card issuers usually must give at least 45 days’ notice before raising interest rates on new purchases after the account’s first year, though exceptions apply and rules vary based on the type of rate change.
Your Credit Card Interest Rate Could Be Variable
A key reason your card’s APR might change is that it’s variable rather than fixed, causing fluctuations.
Variable APRs usually consist of a benchmark rate plus a set margin. When the benchmark rises, your APR can climb based on your card’s terms.
The CFPB points out that an increase in the benchmark tied to your variable rate—like the U.S. Prime Rate—is a valid reason an issuer can raise the rate on your current balance.
How the Federal Reserve Influences Your Credit Card APR
Your credit card’s APR is not directly determined by the Federal Reserve.
Still, the Federal Reserve’s monetary policies can affect market interest rates and the benchmark rates that lenders often follow.
In September 2026, the Federal Open Market Committee increased the federal funds target range by 0.25 percentage points to 3.75%–4.00%. The Fed noted that inflation stayed above its 2% target.
This means if your card has a variable APR, you should monitor Fed rate changes, but those moves don’t automatically cause every credit card’s APR to rise by the same amount.
How and when your APR adjusts depends on your card’s terms and the index that determines your rate.
Your Credit Card Interest Rate May Increase Following a Missed Payment
Missing a payment doesn’t always lead to an immediate rise in your APR.
Still, according to the CFPB, a card issuer can raise the interest rate on your current balance if a minimum payment hasn’t been made within 60 days past the due date, following the rules that apply.
That’s why it’s important to review your payment record before assuming the rate hike is due to Federal Reserve actions.
What Occurs After Missing Payments for 60 Days?
If your rate rose because you were over 60 days late on a payment, there might be a chance to restore your prior rate.
The CFPB states that rate increases tied to payments more than 60 days past due have specific rules.
Because of this, it’s important to review your payment record before assuming the higher APR is permanent.
Your Promotional APR Might Have Ended
A more straightforward reason could be that the introductory promo period has concluded.
For instance, a card might offer an introductory APR of 0% or a low rate for a limited time. After this introductory phase ends, the regular APR specified in your card agreement takes effect.
The CFPB points out that when a temporary rate, like a promotional balance-transfer APR, expires, it can cause the interest rate on an existing balance to change.
Can Your Credit Card Issuer Raise Interest Rates Without Prior Notice?
In most cases, issuers must give you advance warning about major changes, but the notification requirements vary depending on the nature of the rate hike.
The CFPB states that credit card issuers typically must send at least 45 days’ notice before raising the interest rate on new purchases after the first year of your account.
There are key exceptions, such as adjustments related to variable rates and certain other specific cases.
The rules are tighter for existing balances. Typically, issuers cannot raise the interest rate on a current balance unless particular conditions apply.
What to Check on Your Card Statement
If your APR has changed, look through your statement or issuer messages for wording like:
- Annual Percentage Rate (APR);
- Variable APR;
- Prime Rate;
- Effective date;
- Promotional rate expiration;
- Rate change notice.
The effective date is important because the new interest rate might not apply equally to every dollar already owed on your account.
What Could a Higher Credit Card APR Cost You?
The effect depends on your outstanding balance and how quickly you manage to pay it off.
Data from the Federal Reserve in July 2026 show that credit card accounts with interest charges had an average APR of 22.15%.
To illustrate, here’s how the interest on a $5,000 balance changes at different APRs:
This is a basic example assuming your balance remains constant. Actual interest charges depend on your issuer’s method for calculating daily balances and your payment activity.
The key takeaway is clear: higher APRs combined with longer balance carrying periods lead to greater interest costs.
This trend is reflected in the overall debt landscape. According to the New York Fed, U.S. credit-card debt hit $1.263 trillion in Q2 2026, increasing by $21 billion from the prior quarter.
Steps to Take When Your Credit Card Interest Rate Rises
Before you rush to close your card or move your balance, review the details carefully to understand the situation.
Here are some steps you can take instead.
1. Understand Why Your APR Went Up
Contact the phone number on your card’s back or check any notice about rate changes.
Questions to ask:
If the agent explains the hike relates to the Prime Rate, request the current index and margin used to determine your APR.
2. Verify If Your Rate Is Variable
Review your cardholder agreement.
If your APR changes with an index, this might explain the rise. The CFPB notes that an increase in the underlying index is a recognized reason for raising rates on an existing balance.
3. Request a Lower APR From Your Card Issuer
There’s no harm in asking.
Try saying something like:
The CFPB points out that consumers might succeed in lowering their rates by reaching out to issuers, who are also typically required to review certain interest rate hikes periodically after notifying customers.
4. Stop Adding New Charges If Your Balance Is Increasing
Carrying a balance month after month can become more challenging if you keep adding new charges.
This is especially true when consumer revolving credit remains high. According to Federal Reserve figures, revolving credit stood at $1.357 trillion in July 2026.
Whenever you can, try to limit card use to purchases you can pay off quickly to avoid letting your balance—and interest—grow.
5. Carefully Evaluate a Balance Transfer Offer
While a balance transfer might lower your interest costs, don’t base your decision solely on the introductory APR.
Consider these points:
- Fees for balance transfers.
- Duration of the promotional offer.
- Interest rate once the promotion ends.
- If new purchases qualify for the promo rate.
- Your ability to pay off the balance before the promo expires.
A reduced rate only helps if all the terms truly lower your overall borrowing expenses.
Why This Is Especially Important in October 2026
October tends to be a costly month for many families across the U.S.
Costs from Halloween, autumn trips, home expenses, and early holiday shopping often add up on credit cards.
When these charges carry over into future statements, the importance of your APR grows significantly.
October also brings key economic reports that impact financial markets.
The Bureau of Labor Statistics will release September’s CPI on October 14, and the Federal Reserve’s next FOMC meeting is set for October 27–28.
Because of this, October is an ideal time to check your card’s terms before holiday spending picks up.
It’s important to also consider the overall consumer landscape.
The Conference Board revealed that U.S. consumer confidence dropped to 81.9 in September 2026, marking its third consecutive monthly decline amid worries over financial stability, inflation, and the job market.
Put simply, if your budget is already stretched, carrying a balance with a high APR could make the month even tougher financially.
How Your Credit Card Interest Rate Relates to Your Credit Score
A rise in your APR doesn’t always mean your credit score has dropped abruptly.
Several factors can influence how credit cards are priced, such as:
- The card’s benchmark or index.
- The card’s fixed margin.
- Expiration of promotional rates.
- Your payment history.
- Specific terms of your account.
Your credit score remains important when applying for new credit, as lenders often consider it to decide on approval and the conditions they offer.
However, if your current card’s APR has changed, don’t immediately blame your credit score—first review the notice and your card agreement.
When Is It Time to Reach Out to Your Credit Card Issuer?
Consider reaching out to your card issuer if any of the following apply:
- Your APR rose without clear explanation.
- You didn’t get a required notice.
- The rate doesn’t match your card agreement.
- Your promotional APR ended sooner than expected.
- You think a payment was wrongly marked late.
- You want to ask for a lower interest rate.
- You’re having trouble making the minimum payment.
If you suspect your rate was raised in error, the CFPB recommends contacting your card issuer directly.
Should the issue remain unresolved with your issuer, you can file a complaint with the Consumer Financial Protection Bureau for additional help.
Author’s Perspective
It’s easy to overlook a higher APR when you’re just focusing on the figure shown on your monthly statement.
Yet the interest rate is often where the true expense of carrying a credit card balance becomes clear.
Here’s my advice: if you see your credit card interest rate rise, don’t jump to the conclusion you’ve done something wrong, and don’t just accept the new rate without digging into why it changed.
Begin by reviewing your statement. Identify the effective date, confirm if the APR is variable, and check for any expired promos or late payment triggers.
Given today’s conditions, taking that extra step is worthwhile. Credit card debt still exceeds $1.2 trillion, the Federal Reserve reports average interest rates topping 22% on accounts charged interest, and U.S. consumers continue to face high inflation and economic uncertainty.
Recommended Content
Are credit card debts weighing you down?
Learn how personal loans can lower your costs, what rates look like after the Fed’s increase, and when it’s smart to switch cards.
Continue reading * You will remain on the current website